At Vroomdan, we understand that securing the most competitive honda crv financing rates can feel like navigating an absolute maze of confusing credit tiers, dealer sales pitches, and hidden transactional fees. You deserve to drive home a reliable, efficient family SUV without draining your hard-earned bank account on high interest charges that build up over time. Fortunately, learning how to leverage promotional lending specials can unlock incredible savings that you can reinvest directly into your vehicle. Before we dive into our master financing breakdown, you must learn about a critical vehicle shortcut that lets you access your SUV’s most valuable features.
Your CR-V has a secret trick that starts the SUV when your key fob dies.
And 14 other things Honda never told you.
Dead fob fix · Global window down trick · The hidden folding picnic table · Walk Away Auto Lock · and 11 more.
▶ Read Now — Show Me Everything
bryansgarage.com · Bryan Mark
In This Guide
- Lender Channel Comparison: Discover the primary advantages and disadvantages of each financing option.
- OEM Maintenance Integration: Learn how dealer interest campaigns affect your factory service requirements.
- Promo APR Analysis: Evaluate the mathematical difference between low interest rates and direct cash rebates.
- Used Vehicle Strategy: Master the specific factors that control pre-owned financing rates.
Decoding Honda CRV Financing Rates: The Ultimate Guide to Low APR Offers and Specials
Finding the right loan begins with identifying which lending institution best matches your specific credit profile.
Our team has meticulously reviewed the primary automotive lending pathways to save you time and money.
Option 1: Honda Financial Services (HFS)
Honda Financial Services operates as the manufacturer’s dedicated captive lending branch to support vehicle sales.
This institution is responsible for offering the lowest promotional interest rates on brand-new vehicle inventory.
Their primary strength is delivering highly competitive APR specials that are backed directly by factory incentives.
To qualify for their most attractive campaigns, you must maintain an exceptional tier-one credit score of 740 or higher.
Their loan terms are strictly structured with very little room for personalized negotiation if your credit history is imperfect.
Option 2: Local Credit Unions
Local credit unions are member-owned organizations focused on low-cost financial services for local communities.
They are highly compatible with family buyers who prefer customized customer service and flexible repayment windows.
Their biggest advantage is their ability to offer remarkably low rates on high-mileage and pre-owned utility vehicles.
However, you are required to meet specific local residency or employment criteria to establish a membership account.
Additionally, their mobile applications and online loan portals may lack the advanced automation features of global banks.
Option 3: National Banks
National banking institutions use massive capital portfolios to provide automated, rapid credit approvals across the country.
They are perfect for shoppers who already hold active checking accounts and want to consolidate their monthly bills.
Their primary benefit is the convenience of securing an official pre-approval letter within minutes from home.
Unfortunately, their baseline interest rates are typically much higher than factory-backed promotional campaigns.
They also frequently include higher loan origination fees that can silently inflate your overall principal balance.
Selecting the correct lender requires comparing these key operational attributes to align with your monthly budget.
Securing pre-approval before visiting the dealer floor protects you from costly high-pressure showroom tactics.
We have summarized these competing options in the clear comparison table below to simplify your decision.
| Lender Type | Price (Average APR) | Installation Time (Approval) | Durability (Term Options) | Warranty (GAP Protection) |
|---|---|---|---|---|
| Honda Financial Services | Excellent (1.9% – 4.9% APR) | Rapid (Under 30 minutes) | Standard (24 to 72 Months) | Excellent (OEM GAP available) |
| Local Credit Unions | Competitive (4.5% – 6.5% APR) | Moderate (1 to 2 business days) | Highly Flexible (Up to 84 Months) | Good (Affordable third-party options) |
| National Banks | Higher (5.9% – 8.9% APR) | Very Rapid (Instant online check) | Moderately Flexible (36 to 72 Months) | Variable (Higher-cost protection plans) |
Evaluating these channels thoroughly will help you secure the absolute best interest rate for your budget.
By lowering your interest costs, you free up cash flow to invest in top-tier vehicle care guides and preventative maintenance.
To view our seasonal inventory of promotional factory campaigns, read our comprehensive honda crv deals guide.
Understanding How Dealer Finance Specials Impact OEM Parts and Maintenance Requirements
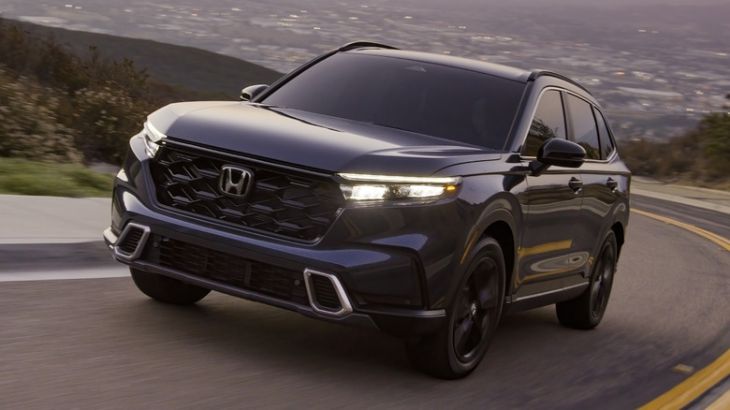
Many buyers are unaware that low APR promotions are frequently connected to strict maintenance compliance terms.
According to official Honda factory manuals, failing to complete scheduled service can complicate future warranty claims.
This standard is highly critical when financing a technologically advanced honda crv hybrid drivetrain.
Lenders have a vested interest in protecting their asset, which means keeping your SUV in peak mechanical condition.
Our ASE Certified Mechanics strongly emphasize using genuine OEM parts for every system repair to prevent premature wear.
Using generic fluids or subpar filters can lead to expensive diagnostics that are incredibly frustrating to pay for out-of-pocket.
Members of the online CR-V Owners Club report that keeping thorough maintenance logs protects the SUV’s long-term resale value.
By scheduling timely fluid changes and safety inspections, you ensure that your financed vehicle remains highly valuable.
Skipping routine maintenance tasks is a surefire way to compromise the structural integrity of your SUV’s drivetrain.
Maintaining a disciplined service schedule guarantees that your financed investment remains fully protected over thousands of miles.
Calculating the Math: Honda CRV Promotional Financing vs. Cash Incentives
Securing a truly low interest rate requires analyzing the real numbers behind “honda crv promotional financing” carefully.
Dealership sales teams often ask you to choose between a low promotional APR and a direct cash-back discount.
If you choose the ultra-low interest rate, you will likely forfeit cash incentives that could immediately lower the loan’s principal.
To find the absolute “best finance rate honda crv” package, you must calculate the total interest paid over the life of your loan.
For a sixty-month term, a lower interest rate almost always beats a small upfront dealer cash discount.
Team Vroomdan recommends using an online auto loan calculator to compare both scenarios before stepping into the showroom.
Taking this simple mathematical step can save you from painful financial regret during your multi-year loan term.
It is incredibly empowering to face a finance manager equipped with exact calculations and accurate rate sheets.
Understanding these mathematical relationships prevents you from agreeing to unnecessary loan options or hidden markups.
Always review the loan contract to confirm there are no prepayment penalties for paying off your balance early.
Leveraging Your Finance Savings for Long-Term SUV Reliability

When you successfully negotiate lower “honda crv finance deals”, your household budget immediately gains extra breathing room.
We recommend dedicating a portion of these monthly savings to build a proactive vehicle maintenance fund.
Replacing your differential fluid and engine filters on schedule prevents costly mechanical issues down the road.
It is also wise to invest in top-tier tires that match your specific trim’s recommended load capacity and performance index.
Addressing minor fluid leaks or worn brake pads immediately prevents small issues from growing into massive repair bills.
This proactive routine is the single most effective way to enjoy a stress-free ownership experience with your family.
To explore flexible, lower-commitment lease options, feel free to read our comprehensive guide on honda crv lease deals.
Your vehicle will reward your financial discipline with smooth operation and exceptional reliability for years to come.
Investing in your SUV’s mechanical health is far more rewarding than sending extra interest dollars to a banking corporate office.
A well-maintained vehicle ensures that your daily work commutes and weekend road trips remain entirely safe.
Avoiding Common Mistakes on Used Honda CRV Financing Rates
One major mistake pre-owned shoppers make is ignoring the impact of vehicle mileage on “used honda crv financing rates”.
Older pre-owned models typically carry higher interest rates from lenders compared to a brand-new 2025 honda crv.
Another frequent slip-up is failing to inspect a vehicle’s detailed maintenance history before signing the loan contract.
Always request a certified vehicle history report to verify that previous owners performed oil changes consistently.
Additionally, many owners make the mistake of relying on expensive dealer service departments for very simple tasks.
You can easily perform basic maintenance like changing cabin air filters and key fob batteries right in your garage.
Taking care of these simple DIY tasks will provide an immense sense of relief and save you hundreds of dollars.
Make sure to watch out for promotional “honda crv loan specials” that hide expensive balloon payments at the end of the term.
Review every page of your contract carefully to prevent the inclusion of unauthorized warranties or luxury dealer add-ons.
Protecting your budget from predatory finance fees allows you to enjoy your CR-V with complete peace of mind.
Frequently Asked Questions
What credit score do I need to secure the lowest honda crv financing rates?
Typically, you will need a credit score of 740 or higher to qualify for the absolute best promotional APR offers from Honda Financial Services.
Buyers with lower credit ratings can still secure highly competitive rates by applying with local credit unions.
Can I refinance my automotive loan if market interest rates fall in the future?
Yes, you can refinance your auto loan at any time to secure a more favorable rate or lower monthly payment.
Refinancing is an incredibly smart financial strategy if your credit score has improved significantly since your initial purchase.
Does promotional financing limit my ability to customize my CR-V?
No, financing your vehicle does not prevent you from adding cosmetic accessories or performing standard DIY upgrades.
However, you must avoid any major mechanical modifications that directly violate your factory warranty terms.
“I’ve driven a CR-V for 4 years and didn’t know this existed.”
— The most common reaction when this article is shared
Did you know your backup camera has a hidden top-down ‘drone view’? Or that your cruise control automatically downshifts on steep mountain hills to save your brakes?
bryansgarage.com · Bryan Mark
Conclusion: Drive Home Smarter with Vroomdan
Securing competitive honda crv financing rates lets you enjoy your SUV affordably.
Combining smart financial strategy with proactive DIY maintenance maximizes your vehicle’s lifespan.
Ready to get the most out of your SUV? Check out more guides on Vroomdan or email us at contact@vroomdan.com — our team is here to help you discover more SUV secrets and maintenance guides.